
When some individuals borrow money from official financial institutions—such as banks or microfinance organizations—it often reflects underlying economic and social challenges that can hold back a country’s progress.
A low level of formal borrowing typically indicates that a large share of the population is excluded from the financial system.
Many people may lack access to bank accounts, credit histories, or even basic financial literacy. Instead, they rely on savings, family support, or informal lenders.
On the other hand, a small number of people borrowing formally could also suggest self-sufficiency.
Such an indicator may simply mean that the average household does not need loans, as it already earns enough to sustain itself.
However, when it comes to businesses—whether large companies or small and medium-sized enterprises (SMEs)—it is easy to deduce that a low rate of formal borrowing signals a lack of access to credit.
SMEs typically depend on loans to start operations and are responsible for creating most jobs in developing countries. Entrepreneurs without adequate financing cannot purchase equipment, hire workers, or launch new projects.
A low level of formal borrowing encourages consumers to turn to informal lenders or community credit networks. While these may be helpful in emergencies, they often come with very high interest rates and offer no consumer protection. Borrowers can quickly fall into debt cycles, deepening poverty and financial instability.
Conversely, borrowing from regulated financial institutions helps individuals build credit histories and can open the door to future opportunities such as mortgages, business loans, or student financing.
In many African countries, formal borrowing remains low despite the rise of fintech and mobile money.
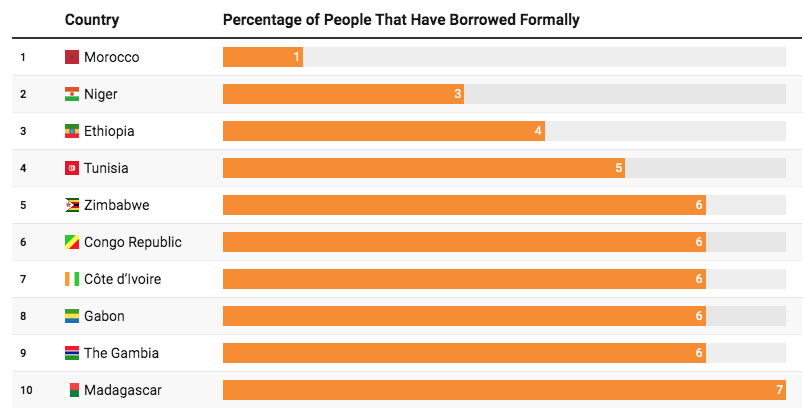
Below are the African countries with the smallest share of people who have borrowed money formally from a financial institution, according to a World Bank report.
Source: Bussiness insider Africa