The PROPRIV process is moving into its most ambitious phase. What Angolan investors need to know — and question — before making a decision.
When Banco Angolano de Investimentos carried out the first Angolan IPO in 2022, many people watched from a distance. When Banco de Fomento Angola raised 241 million dollars in September 2025 — and its shares more than doubled in the first days of trading — that distance began to feel costly. Now come the two heaviest names in the Angolan economy: Sonangol and Endiama. This time, staying out could be a decision investors regret — or, if they are not careful, a decision they regret for completely opposite reasons.
What Is PROPRIV — And How Did We Get Here
Angola did not begin with a stock exchange. It began with oil, diamonds, and an economy structured around the state. For decades, major national companies were effectively extensions of public power — without market transparency, without shares in circulation, and without accountability to investors.
PROPRIV was created to change that reality. Launched in 2019 by President João Lourenço, the programme initially aimed to privatise 195 public assets by 2022. The first phase concluded with 96 privatisations and raised more than 1.1 billion dollars. The results were considered positive, but insufficient.
In 2023, the programme was renewed through Presidential Decree No. 78/23, extending it to 2026 with 73 additional assets to privatise. The second phase includes the names everyone has been waiting for: Sonangol and Endiama — the two crown jewels of the Angolan economy.
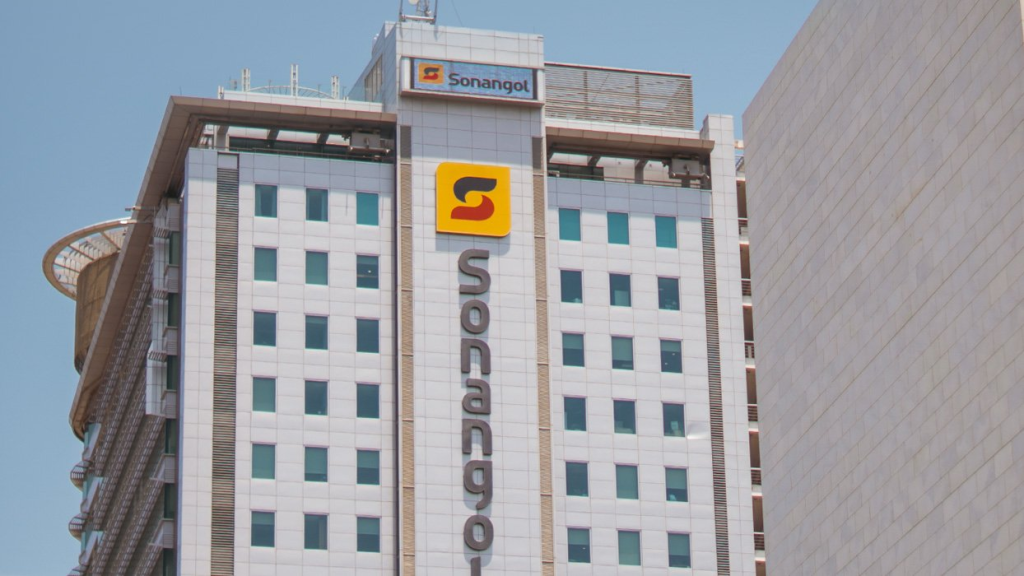
Sonangol: Angola’s Most Important Company About To Be Listed
Sonangol is Africa’s second-largest oil producer and the backbone of Angola’s public finances. Talking about Sonangol is essentially talking about the Angolan state. For this reason, its IPO process is both the most anticipated and the most complex.
The government plans to sell up to 30% of Sonangol’s capital on BODIVA, in a phased operation involving both local and international investors. In February 2026, a board member confirmed to Bloomberg that IPO preparations are ongoing — the company has already completed bond issuances and created an investor relations office, both key steps toward listing.
However, one central condition has delayed the process: the removal of fuel subsidies. The Angolan government believes Sonangol’s listing only makes full sense — and will achieve a fair valuation — once the company operates under true market conditions, without price distortions. The IPO timeline remains uncertain, with some sources pointing to 2027 as a more realistic horizon.
What is certain is that Sonangol is already present on BODIVA through private bonds admitted to trading in September 2023. The equity listing is the next step — and when it happens, it is expected to be the largest capital markets operation in Angola’s history and one of the largest in Africa.
Endiama: The Diamond Giant Yet To Shine On The Marke
Endiama is the National Diamond Company responsible for Angola’s diamond sector. Angola is one of the world’s largest diamond producers, and Endiama holds stakes in multiple mining concessions across the country.
The company’s IPO is also included in the PROPRIV 2023–2026 framework. However, unlike Sonangol — which has already taken concrete steps toward the market — Endiama’s process remains less transparent in terms of timing and structure. What is known is that BODIVA aims to reach 10 listed companies by 2027, with Endiama part of that target.
The complexity of the mining business — including geological risks, international joint-venture contracts, and diamond price volatility — makes valuation particularly challenging. Investors considering Endiama’s IPO will need to do significantly more due diligence.
What We Learned From The BFA IPO — And What It Says About The Future
The IPO of Banco de Fomento Angola in September 2025 served as a live test of Angola’s capital market potential. Demand was five times higher than supply. More than 11,000 investors applied. Shares doubled in the first days of trading.
This outcome has two interpretations. The optimistic view suggests that Angolan investors are ready for capital markets, that there is accumulated savings waiting for productive investment, and that strong companies will always be well received. The cautious view warns that such excessive demand can create unrealistic expectations of immediate gains — and that not all IPOs will resemble a bank with 3 million clients and 194 branches.
Sonangol and Endiama are fundamentally different from Banco de Fomento Angola. They are more exposed to commodity volatility, have more complex cost structures, and their valuation depends on external variables such as oil prices, global diamond demand, and OPEC decisions.
The Four Questions Investors Should Ask Before Subscribin
Subscribing to an IPO is not the same as buying a lottery ticket. It is an investment decision that requires analysis. Before entering, Angolan investors should ask four key questions:
1. What does the prospectus say?
Every IPO should have a public document describing the company, historical results, risks, and use of proceeds. Read it carefully. If it is not available or accessible, be cautious.
2. At what price am I buying?
IPO pricing is not automatically cheap. Understand implied valuation multiples (P/E, P/B) and compare them with similar companies.
3. What is my investment horizon?
A 95% first-day gain, as seen with Banco de Fomento Angola, is exceptional and unlikely to repeat. If you need short-term liquidity, commodity-heavy IPOs may not be suitable.
4. What is my total exposure to Angola risk?
If your salary, business, and savings already depend on the Angolan economy, adding Sonangol shares increases risk concentration rather than diversification.

What The CMC And BODIVA Need To Get Right
The success of upcoming IPOs depends not only on companies, but also on supervision quality and market conditions. The Comissão do Mercado de Capitais launched a Regulatory Agenda and Financial Education Programme in 2026 — positive signals. But the real test will come with Sonangol’s prospectus.
The market must ensure audited and publicly accessible financial information, transparent IPO pricing mechanisms, sufficient secondary market liquidity, and clear protection mechanisms for minority investors.
Without these conditions, early enthusiasm could turn into frustration — and frustration in an immature capital market takes years to recover.
The IPOs of Sonangol and Endiama represent a turning point in Angola’s economic history. For the first time, ordinary citizens may become co-owners of the oil and diamond companies that finance the state. That is, in itself, historic and worth acknowledging.
But responsible participation requires information, not euphoria. Prepared investors may benefit from a generational opportunity. Those driven only by excitement risk paying a price they did not understand.
Source: O Telegrama