Angola’s accounting profession faces its most demanding modernisation test yet, with a mandatory transition to International Financial Reporting Standards (IFRS) set for 1 January 2027 — and experts are warning that the country is running out of time to prepare.
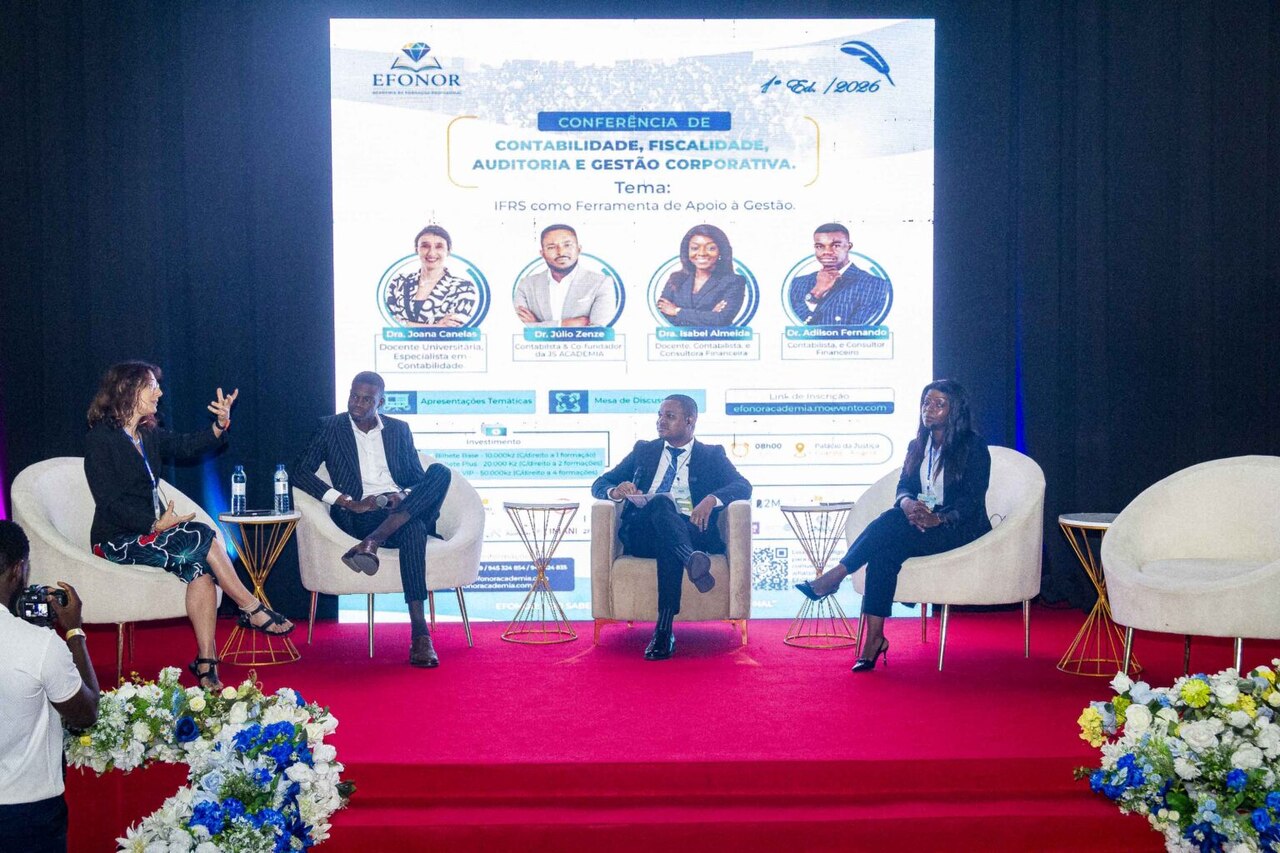
The alarm was sounded at the 1st Conference on Accounting, Taxation, Audit and Corporate Governance, held on 25 July at the Auditorium of the Palace of Justice in Luanda. The event brought together professionals, academics and sector specialists to examine the challenges posed by the mandatory adoption of IFRS — first in the insurance sector, with subsequent extension to the non-financial sector.
The current state of financial reporting in Angola is marked by stark asymmetries: company reports range from three to hundreds of pages, some audited, many not. Participants said this disparity underscores the urgent need for standardisation. Yet the transition to the new framework is obstructed by three structural barriers that, according to conference participants, cannot be allowed to linger.
The first of these concerns the introduction of IFRS 18, which represents a quiet but far-reaching revolution in the presentation of financial statements. The standard eliminates the traditional logic of classifying results by nature and imposes a framework based on cash flows, fundamentally altering how companies disclose their financial performance.
The problem, experts noted, is that the preparation of cash flow statements has historically been the weakest point in Angola’s national accounting practice. Most professionals trained in recent years have had little or no practical exposure to this methodology. Without intensive and immediate technical retraining, the risk of distortions in financial reporting is high — undermining the very transparency that IFRS is designed to guarantee.
The transition cannot be resolved through theoretical training alone. Information systems currently in use — designed primarily for Angola’s General Accounting Plan (Plano Geral de Contabilidade, or PGC) — lack the functionality to process fair value measurements, asset impairments and the complex disclosures required under international standards. Software providers will need to adapt or replace their platforms, an investment that many Angolan companies have yet to factor into their planning.
Even more concerning, according to conference participants, is the lag in higher education. Universities and polytechnic institutes continue to graduate students whose curricula make little or no reference to IFRS, while what technical capacity-building does exist is largely confined to one-off sessions concentrated in Luanda. This training blackout creates a worrying gap: the market will need hundreds of qualified professionals by 2027, yet academic institutions are still producing graduates unfamiliar with the new rules. The decentralisation of training to the country’s other provinces was identified as a pressing and as yet unaddressed need.
The second major obstacle is a legal and fiscal labyrinth that lacks transitional provisions. The most significant external barrier to IFRS adoption lies in its incompatibility with Angola’s current tax regime. National tax law does not recognise key IFRS concepts such as fair value, creating a disconnect between a company’s accounting result and its taxable result.
Without prior legislative adjustments, companies risk double taxation or protracted tax disputes. Compounding the problem is Angola’s legislative volatility — with frequent tax amendments — which generates uncertainty and inhibits medium-term planning. Experts at the conference argued forcefully for the creation of transitional rules that would allow an adaptation period without immediate penalties. As yet, however, there are no concrete signs of progress on that front.
The third pressure point concerns key sectors already facing demands from foreign investors. The oil, telecoms and manufacturing sectors — all with significant international exposure — are already under pressure from foreign investors to align their reporting with global standards.
The message from conference experts on this point was unambiguous: waiting for the final publication of local implementing regulations before beginning preparations is a high-risk strategy. The international standards are already available, and self-study combined with continuous professional development are currently the only viable tools for managing the transition risks.
The transparency and credibility that IFRS promises are worthwhile goals, participants said, but they will not be achieved without confronting three concrete obstacles head-on: the technical weakness of the professional workforce, the academic vacuum in higher education institutions, and the misalignment between the new accounting standard and Angola’s fiscal framework.
With 2027 now approaching rapidly, the message from the specialists gathered in Luanda was unequivocal: those who wait, lose.
The conference, the first of its kind in Angola, signals a growing recognition within the profession that the countdown to the IFRS deadline demands coordinated action across regulators, educators, software developers and the corporate sector — and that the window for orderly preparation is narrowing.

Source: Mercado / Original article: https://mercado.co.ao/angola-enfrenta-corrida-contra-o-tempo-para-adoptar-as-ifrs-ate-2027/