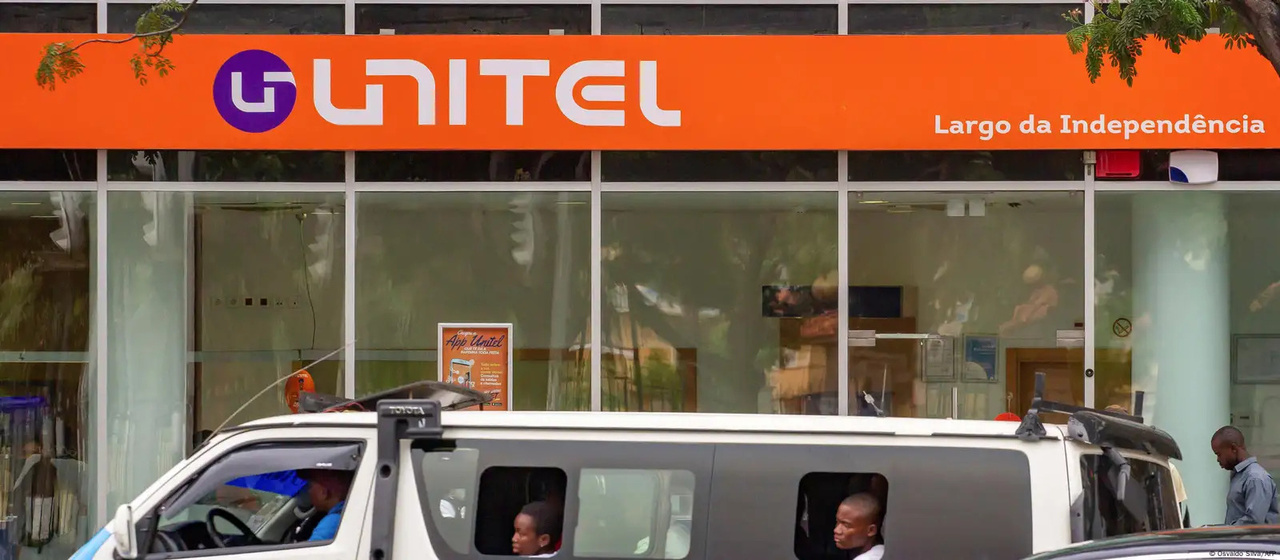
The sale on the stock exchange of a portion of Unitel’s share capital could take place at the end of July, in an operation seen as a step in consolidating and redefining Angola’s capital market. While investors are highly expectant, there is also a “silent war” among intermediaries, as new rules are being considered to contain risks and allow participation only from operators with software integrated with commercial banks to enable automatic fund blocking and settlement.
This behind-the-scenes conflict has reached the office of Finance Minister Vera Daves de Sousa, who oversees state holdings being listed on the stock exchange. O Telegrama is awaiting a statement from IGAPE and from the operator responsible for structuring the transaction.
BFA Capital Markets, as the structuring agent of Unitel’s Initial Public Offering (IPO), carried out under the Privatization Programme (PROPRIV), plans to introduce new eligibility requirements for placement agents in the sale of 15% of the share capital of Angola’s largest mobile telecom operator.
According to available information, the measure aims to make the market more robust and secure, for example by avoiding calculation errors during allocation of proceeds and ensuring that participating investors actually have funds available and blocked in settlement banks.
However, the new requirements have divided brokers, as most operators do not have automated fund blocking and settlement systems known as Application Programming Interfaces (APIs), which enable direct execution of these processes.
An incomplete survey by O Telegrama shows that, out of 24 intermediaries registered with the Capital Markets Commission (CMC) and authorised to operate on the Angolan Debt and Securities Exchange (BODIVA)—comprising 14 brokerage firms and 10 securities dealers—only five have this software integrated with commercial banks for automated fund blocking and financial settlement.
Those with such systems include Áurea SDVM (via Banco Angolano de Investimentos), Hemera Capital Partners Securities (via Banco Millennium Atlântico), Prime Solutions SCVM (via Banco de Comércio e Indústria), Standard Invest SDVM (via Standard Bank Angola), and BFA Capital Markets SDVM (via Banco de Fomento Angola). For the remaining firms, it was not possible to confirm whether Banco Caixa Angola and brokerage firm Prospectum Capital have such systems.
“A Step Back for the Market”
Concerned about the selection process, several intermediaries have expressed strong reservations about the model adopted for the Unitel IPO, arguing that it would represent a setback for the development of Angola’s capital market.
This disagreement is also reflected in a letter sent to Finance Minister Vera Daves de Sousa, as the official responsible for state holdings in Unitel through IGAPE. In the letter, brokers stress that the market is still in a consolidation and growth phase, and that restricting participation could hinder the balanced development of the capital markets ecosystem and reduce incentives for its participants to evolve.
Regarding current technological mechanisms—namely the Capizar platform—the document acknowledges that, like any evolving system, there is room for improvement, particularly in innovation, operational efficiency, and user experience.
The signatories warn that abrupt changes may create asymmetries or limit participation by duly registered market agents. They also argue that market participants have structured their investments and operational models based on the existing regulatory framework and requirements set by competent authorities.
They therefore call for any significant changes to participation conditions in such operations to be preceded by proper communication, clear justification, and reasonable adaptation periods, ensuring legal certainty and regulatory predictability.
“Given the above, we respectfully call on the competent authorities to ensure this process is guided by the principles of transparency, proportionality, predictability and inclusion, ensuring that the evolution of Angola’s capital market occurs through sustained and balanced improvements,” the letter concludes.
“It Is a Necessary Requirement”
Some capital markets stakeholders interviewed by O Telegrama support the new requirement for selecting placement agents, both for the Unitel share sale and for future operations.
“In a market like ours, where financial literacy is still low, there is a perception that all operators can participate equally, when in practice there is a huge difference between having a licence and ensuring security,” said a senior executive at an investment fund management company.

Speaking anonymously, another senior executive specializing in financial structuring and advisory argued that the key issue is ensuring that orders are backed by available funds. “This eliminates the risk of an investor placing a buy order without sufficient money in their account.”
In the same vein, another executive stated that many operators active in the stock market lack proper risk-control infrastructure. “They operate almost manually. We are talking about real risk—brokerage firms still using Excel in high-value operations,” he said.
Source: O Telegrama